

ASC 606 Revenue Recognition: The Five Steps for Subscription, Usage, and Hybrid Models
20 MIN READ
|
Updated on September 18, 2026

ASC 606 is the FASB standard governing revenue recognition from customer contracts, using a single five-step model — converging with IFRS 15 but diverging in practice across US and international entities.
The five steps are deceptively simple — complexity hits the moment revenue moves beyond flat subscriptions into usage, credits, overages, and agentic contracts.
The model still applies — but identifying obligations, estimating variable consideration, and timing recognition is what breaks spreadsheet-and-ERP stacks.
Chargebee RevRec closes the gap by recognizing revenue on the same platform that meters and bills hybrid models.
The five steps of revenue recognition under ASC 606 are: identify the contract, identify the performance obligations, determine the transaction price, allocate that price to the obligations, and recognize revenue as each obligation is satisfied.

Together they form the ASC 606 five-step model, a reusable framework that applies to every contract regardless of pricing shape.
A contract exists when both parties approve it, rights and payment terms are identifiable, and collection is probable. For a subscription business, the order form, the click-through agreement, and the renewal all qualify. The judgment gets harder with mid-term amendments, co-terms, and ramp deals, where one commercial relationship spans several overlapping agreements.
A performance obligation is a distinct promise to transfer a good or service to the customer. A single contract can hold several: platform access, onboarding, premium support, and metered application programming interface (API) calls. Each distinct promise is recognized on its own schedule, so identifying them correctly is where recognition either stays clean or starts to drift.
The transaction price is the consideration you expect in exchange for satisfying the obligations. For a flat subscription, it’s the contract value. For usage, credits, and overages, part of the price is variable, so you estimate it using either the expected-value or most-likely-amount method and constrain it to the amount that won’t reverse.
You allocate the transaction price across obligations based on their standalone selling price, the price you’d charge for each element sold on its own. When an element has no observable standalone price, you estimate it. Bundled deals and discounts make this the step most prone to manual error in a spreadsheet stack.
You recognize revenue when control transfers, either over time or at a point in time. Subscription access transfers over time, so it’s recognized ratably. Usage transfers as consumed. Getting the timing right per obligation is the whole game, and it’s exactly where flat-subscription assumptions fall apart.
The steps read cleanly on paper. They start to strain the moment a contract carries more than one obligation or a price that moves with usage.

You recognize usage-based revenue as it’s consumed, not when it’s billed, because the performance obligation is satisfied as the customer uses the service.
This is the single biggest gap in most inherited finance stacks.
Usage revenue is invoiced in arrears, so the billing system posts a lump at the invoice date while the general ledger needs it spread across the consumption period. When the two disagree on when revenue is earned, finance is flying blind until close, then reconciling by hand.
Usage-based pricing is now the norm rather than the exception. 51% of recurring-revenue companies combine subscription with usage- or outcome-based pricing, while 75% retain a subscription element.
The operational friction is real: the top challenge in usage-based pricing is explaining the pricing structure to customers, followed by building and maintaining the metering infrastructure.
Metered charges, whether API calls, tokens, or compute hours, are recognized in the period the usage occurs. If a customer consumes across March and you invoice in early April, the revenue belongs to March. Recognizing it at the invoice date overstates April and understates March, which is a misstatement risk an auditor will catch.
Where usage isn’t yet billed at period-end, you estimate the variable consideration and recognize the accrued amount, constrained so it’s highly probable it won’t reverse. This is where the engineering and product owners of the metering data become co-equal stakeholders with finance: recognition is only as accurate as the consumption data feeding it.
Chargebee RevRec ingests usage events and applies recognition rules for metered, consumption-based, and prepaid credit drawdown revenue directly, without manual allocation.

Revenue recognition for hybrid pricing works by decomposing the contract into separate performance obligations, each with its own timing, then recognizing each element on its correct schedule. A hybrid deal carries several distinct obligations to recognize, and a spreadsheet stack forces a manual reallocation every time a new pricing model launches. Hybrid is spreading for a sound reason: 67% of companies using a hybrid pricing model expect improved margins, compared with 32% of those on pure usage-based pricing.
A seat-plus-usage contract carries at least two obligations. The seat license is a right to access, recognized ratably over the term. The usage tiers are consumption, recognized as used. You allocate the transaction price across both by standalone selling price, then run two timing treatments inside one contract. T2D2 grew revenue 3x in 24 months with Chargebee, using flexible seat-based licensing with usage tiers.
A minimum commitment is a fixed floor recognized over the commitment period, while overages above the floor are variable consideration recognized as consumed. The estimation question is whether the customer will exceed the commit, and by how much, which you constrain until it’s highly probable.
Prepaid credits create a contract liability at purchase, not revenue. You recognize revenue as the customer draws down credits against services, matched to the underlying performance obligation. Breakage, the credits that expire unused, is estimated and recognized over the pattern of expected usage.
Chargebee RevRec handles seat, usage, and credit models from a single configurable revenue recognition rules engine, so a new pricing feature doesn’t trigger an engineering ticket to change how revenue is recognized.
You recognize revenue for AI-native, agentic, and outcome-based contracts by asking what the performance obligation is, then timing recognition to when that obligation is satisfied. When the customer pays for an outcome or an agent action rather than seat access, the recognition trigger shifts from the passage of time to the delivery of the result. This is white-space territory, and it’s where the engineering and product owners of the metering data carry the recognition question, because the data that proves an outcome occurred is data they control.
If the customer pays only when an agent completes a resolved ticket, a booked meeting, or a successful transaction, the obligation is the outcome, and revenue is recognized when the outcome is delivered and measurable. Access alone doesn’t satisfy the obligation, so ratable treatment would be wrong. The practical requirement is an auditable record of each outcome event, tied back to the contract term that priced it.
Outcome-based and agentic pricing is variable by design, so you estimate the consideration and constrain it to the amount that won’t reverse, then true up as actual outcomes land. The volume and timing of agent actions are hard to forecast, which makes the metering feed the backbone of recognition. Chargebee’s AI-native and agentic billing positioning treats this consumption data as a first-class input to recognition, not an afterthought bolted on after billing.
Revenue Recognition
IFRS 15 and ASC 606 share the same five-step model because FASB and the International Accounting Standards Board (IASB) developed them jointly, so the core principle is the same on both sides of the Atlantic.
The differences show up in practice, and a business closing books across US and international entities can’t assume one standard’s treatment carries to the other. Divergence creates restatement and audit risk at consolidation. The five-step model here interlinks with the deeper treatment in our guide on how to identify the contract under ASC 606 and IFRS 15.
Both standards use the same five steps, the same core control-transfer principle, and the same broad approach to identifying performance obligations and allocating the transaction price. For a straightforward subscription recognized ratably, the treatment is generally consistent under either standard.
Both standards share the same five-step revenue recognition model, so the framework a finance team applies looks familiar across US and international entities. The practical differences surface at consolidation, when you close books under US Generally Accepted Accounting Principles (US GAAP) for one entity and IFRS for another. Four areas matter most for a business reporting across US and international geographies.
Area | ASC 606 (US GAAP) | IFRS 15 |
|---|---|---|
Collectibility threshold | ‘Probable’ interpreted as about 75% likelihood (PwC guidance) | ‘Probable’ means more likely than not, greater than 50% (PwC guidance) |
Licenses of intellectual property | Explicit functional vs symbolic IP classification (IASB review) | Principles-based paragraph B56 access-vs-use criteria (IASB review) |
Impairment reversal of contract costs | Reversal of a prior impairment loss is prohibited (Deloitte DART) | Reversal is required when impairment conditions cease (KPMG analysis) |
|
Interim-period disclosures | More extensive interim disclosures for public entities (KPMG analysis) | Fewer interim disclosures; disaggregated revenue only (KPMG analysis) |
Chargebee RevRec supports recognition across multiple legal entities and currencies from one system.
You handle variable consideration by estimating it and constraining it, contract modifications by determining whether they create a new contract or adjust the existing one, and multi-element arrangements by allocating the transaction price across obligations by standalone selling price. These three are where a spreadsheet stack generates audit exceptions, because each upsell, downgrade, co-term, and credit note forces a manual reallocation, and every manual step is a place an error can hide.
Variable consideration covers usage, overages, rebates, and outcome-based fees. You estimate the amount, then apply the constraint so you only recognize what’s highly probable not to reverse.
Contract modifications hinge on a test: a modification that adds distinct goods or services at their standalone price is a separate contract, while one that changes the scope or price of existing obligations is a prospective or cumulative catch-up adjustment. Multi-element arrangements come back to the standalone selling price and a defensible SSP library that holds up under audit.
Chargebee RevRec automates modification handling and maintains a configurable SSP library so reallocation happens without manual journal entries.
ASC 606 compliance matters because it makes revenue comparable across companies, keeps you audit-ready, and clears the path to an initial public offering (IPO) or a first external audit.
Get it wrong and the cost is concrete: restatement, audit exceptions, and blocked IPO readiness. Scale makes the stakes higher. 96% of subscription businesses expected to grow in 2025, with roughly two-thirds anticipating growth faster than 20% year over year. More growth means more contracts, more pricing variants, and more recognition judgment calls to defend.
ASC 606 gives investors a consistent basis to compare revenue across companies, which is why auditors scrutinize how you apply it. Audit-ready means every recognition decision carries a timestamped trail from the source contract to the journal entry. When that trail is assembled by hand at close, finance ends up working weekends at month-end to reconstruct it.
A first institutional audit or an IPO filing raises the bar from “books that balance” to “recognition policy a Big Four auditor and the Securities and Exchange Commission (SEC) will sign off on.” That means documented SSP methods, defensible variable-consideration estimates, and a complete audit trail. Building that evidence retroactively is where timelines slip.
Chargebee RevRec is positioned to produce this documentation automatically as part of the ASC 606 implementation rather than as a manual scramble before the deadline.
A software-as-a-service (SaaS) company should look for revenue recognition software that handles usage-based accruals, automates contract modifications, maintains a full audit trail, posts clean summarized entries to the general ledger, and implements in weeks.
ERP modules and spreadsheets tend to fail on the first two: usage-based accruals and amendment handling are exactly where they force manual work and generate exceptions.
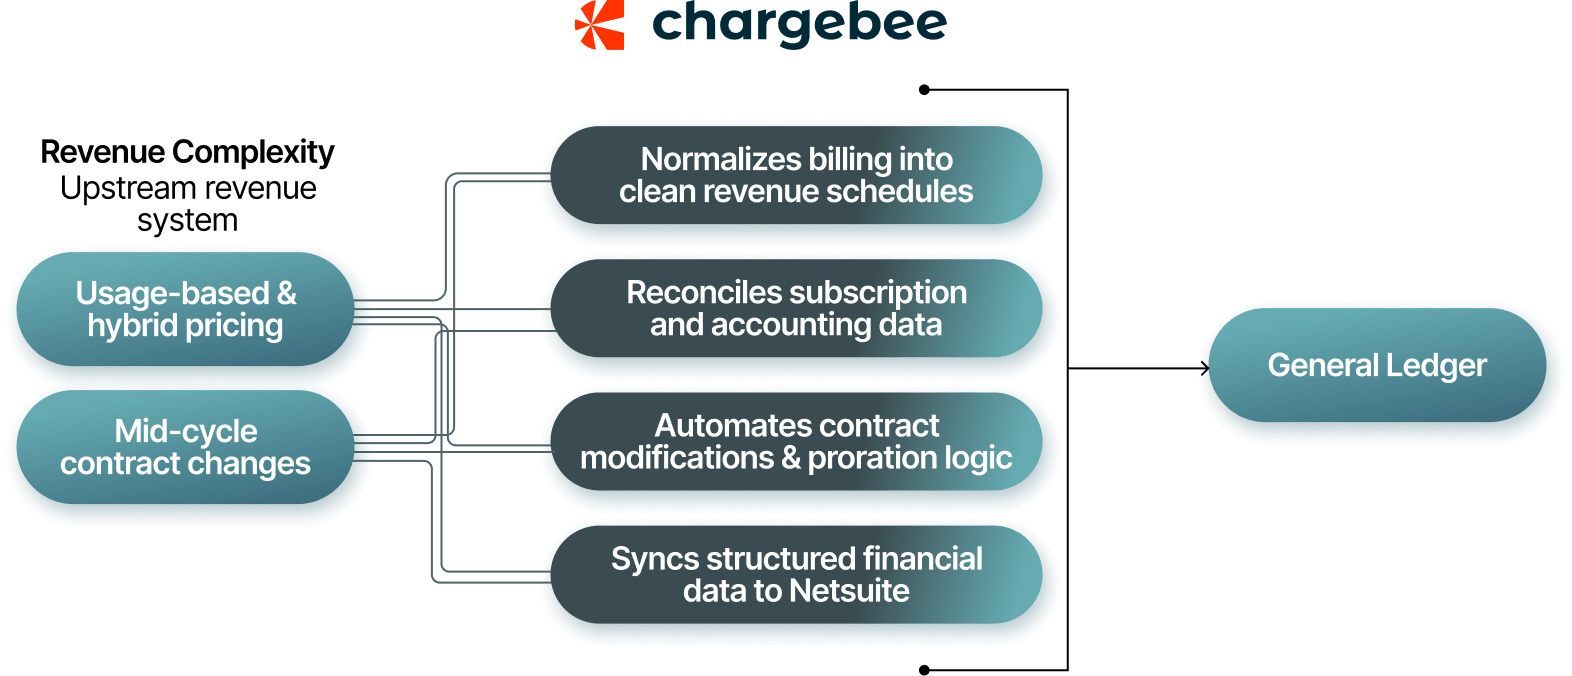
The right tool sits as a subledger between your billing system and your general ledger, absorbing recognition complexity and posting a clean, period-level number downstream.
Use these evaluation criteria:
Usage and consumption handling: native recognition of metered, credit, and consumption revenue as a built-in feature.
Contract modification automation: upsells, downgrades, co-terms, and credit notes reallocated without manual journal entries.
Audit trail: a complete, timestamped record from source contract to journal entry.
General ledger posting: summarized, period-level entries that keep the ledger clean.
Implementation time: weeks rather than multi-quarter projects, which matters when an audit or funding deadline is close.
Chargebee RevRec is a revenue subledger that sits between billing systems and the general ledger, working alongside systems like NetSuite by feeding them clean summarized journal entries.
Chargebee was named a Leader in the 2026 Gartner Magic Quadrant for Recurring Billing Applications.
This matrix maps each monetization model to how the ASC 606 steps change, and it’s the piece most standard explainers skip. As a reminder, 51% of recurring-revenue companies now combine subscription with usage- or outcome-based pricing, so more than half of finance teams are working across several of these rows at once.
| Pricing model | Obligation identification | Variable consideration estimation | Allocation | Timing |
|---|---|---|---|---|
| Pure subscription | Single access obligation | None; price is fixed | Not required; one obligation | Ratable over the term |
| Seat + usage tiers | Seat access plus metered usage | Estimate the usage portion, constrained | By standalone selling price across both | Seat ratable; usage as consumed |
| Prepaid credits / tokens | Contract liability until drawdown | Estimate breakage on unused credits | Matched to the drawn-down obligation | On drawdown, plus breakage over expected usage |
| Pure consumption | Usage as the performance obligation | Estimate unbilled usage at period-end | Not required; single usage obligation | As consumed |
| Outcome / agentic | The delivered outcome or agent action | Estimate outcome volume, constrained; true up | Matched to each priced outcome | When the outcome is delivered and measurable |
ASC 606 stands for Accounting Standards Codification Topic 606, the US revenue recognition standard issued by FASB for revenue from contracts with customers.
The five steps are: identify the contract, identify the performance obligations, determine the transaction price, allocate the transaction price to the obligations, and recognize revenue as each obligation is satisfied.
They converge on the same five-step model because they were developed jointly, but they diverge in practice, so multi-geography businesses treat them separately. See the IFRS 15 section above for the specific divergence points.
You recognize usage-based revenue as it’s consumed, not when it’s billed, because the performance obligation is satisfied as the customer uses the service. Where usage is unbilled at period-end, you estimate and accrue the constrained amount. This matters because 51% of recurring-revenue companies now combine subscription with usage- or outcome-based pricing.
ASC 606 revenue recognition software is a subledger that sits between your billing system and your general ledger, applies recognition rules automatically, and posts clean summarized journal entries with a full audit trail. Chargebee RevRec is one such product built for subscription and usage-based businesses.
The ASC 606 five-step model hasn’t changed, but the contracts it governs have.
Subscription revenue recognized ratably was the easy case. Usage, hybrid tiers, prepaid credits, and outcome-based agentic deals each carry a different obligation and a different recognition trigger — and reconciling them by hand is where audit exceptions and blown close deadlines come from.
The model-by-model reality is that most finance teams now work several pricing rows at once.
Recognizing that revenue accurately depends on the same consumption and contract data that bills it.

